

Imperia Sensa Park, MIK Group’s project of 922 high-rise apartments on Vo Chi Cong Street in Phuoc Long Ward, Ho Chi Minh City, has the most complex sales policy of the three projects I analyzed: five payment schemes, discounts from 1.5% to 14%, weekly Early Bird offers and the “Settle in, Earn more” program tied to a CAKE digital-bank savings account. This article reruns each scheme on a 3-bedroom unit and reads the savings program’s conditions closely, so you can tell which benefits are real and which are just presentation.
The Imperia Sensa Park policy has changed by phase: Early Bird 2% (29 September to 18 October 2026), then Early Bird 1.5% for every unit plus an extra 0.5% for units of 2 bedrooms and above (19 to 25 October 2026). Both windows have ended. What remains, the scheme discounts and the “Settle in, Earn more” program, is the framework you need to understand when dealing with the developer.
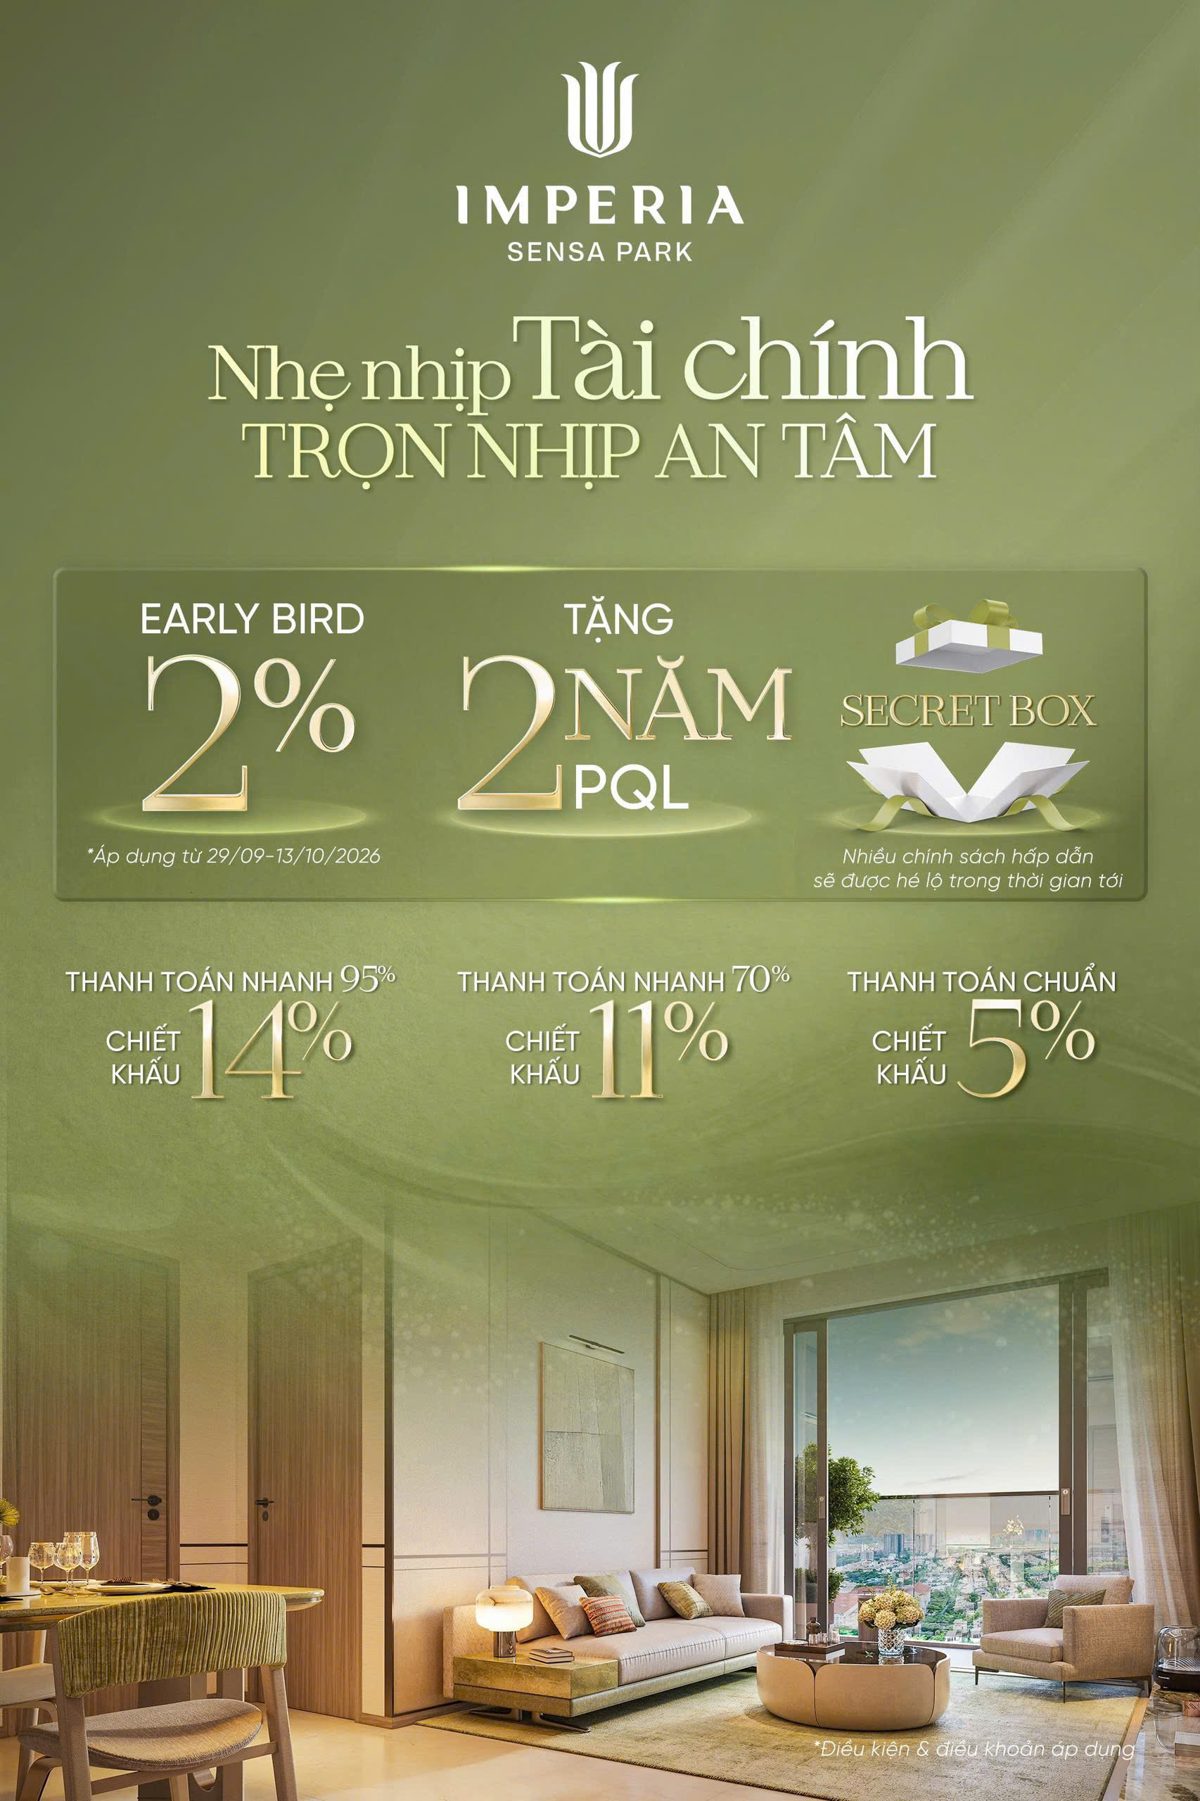
Imperia Sensa Park sales policy at a glance (updated November 2026)
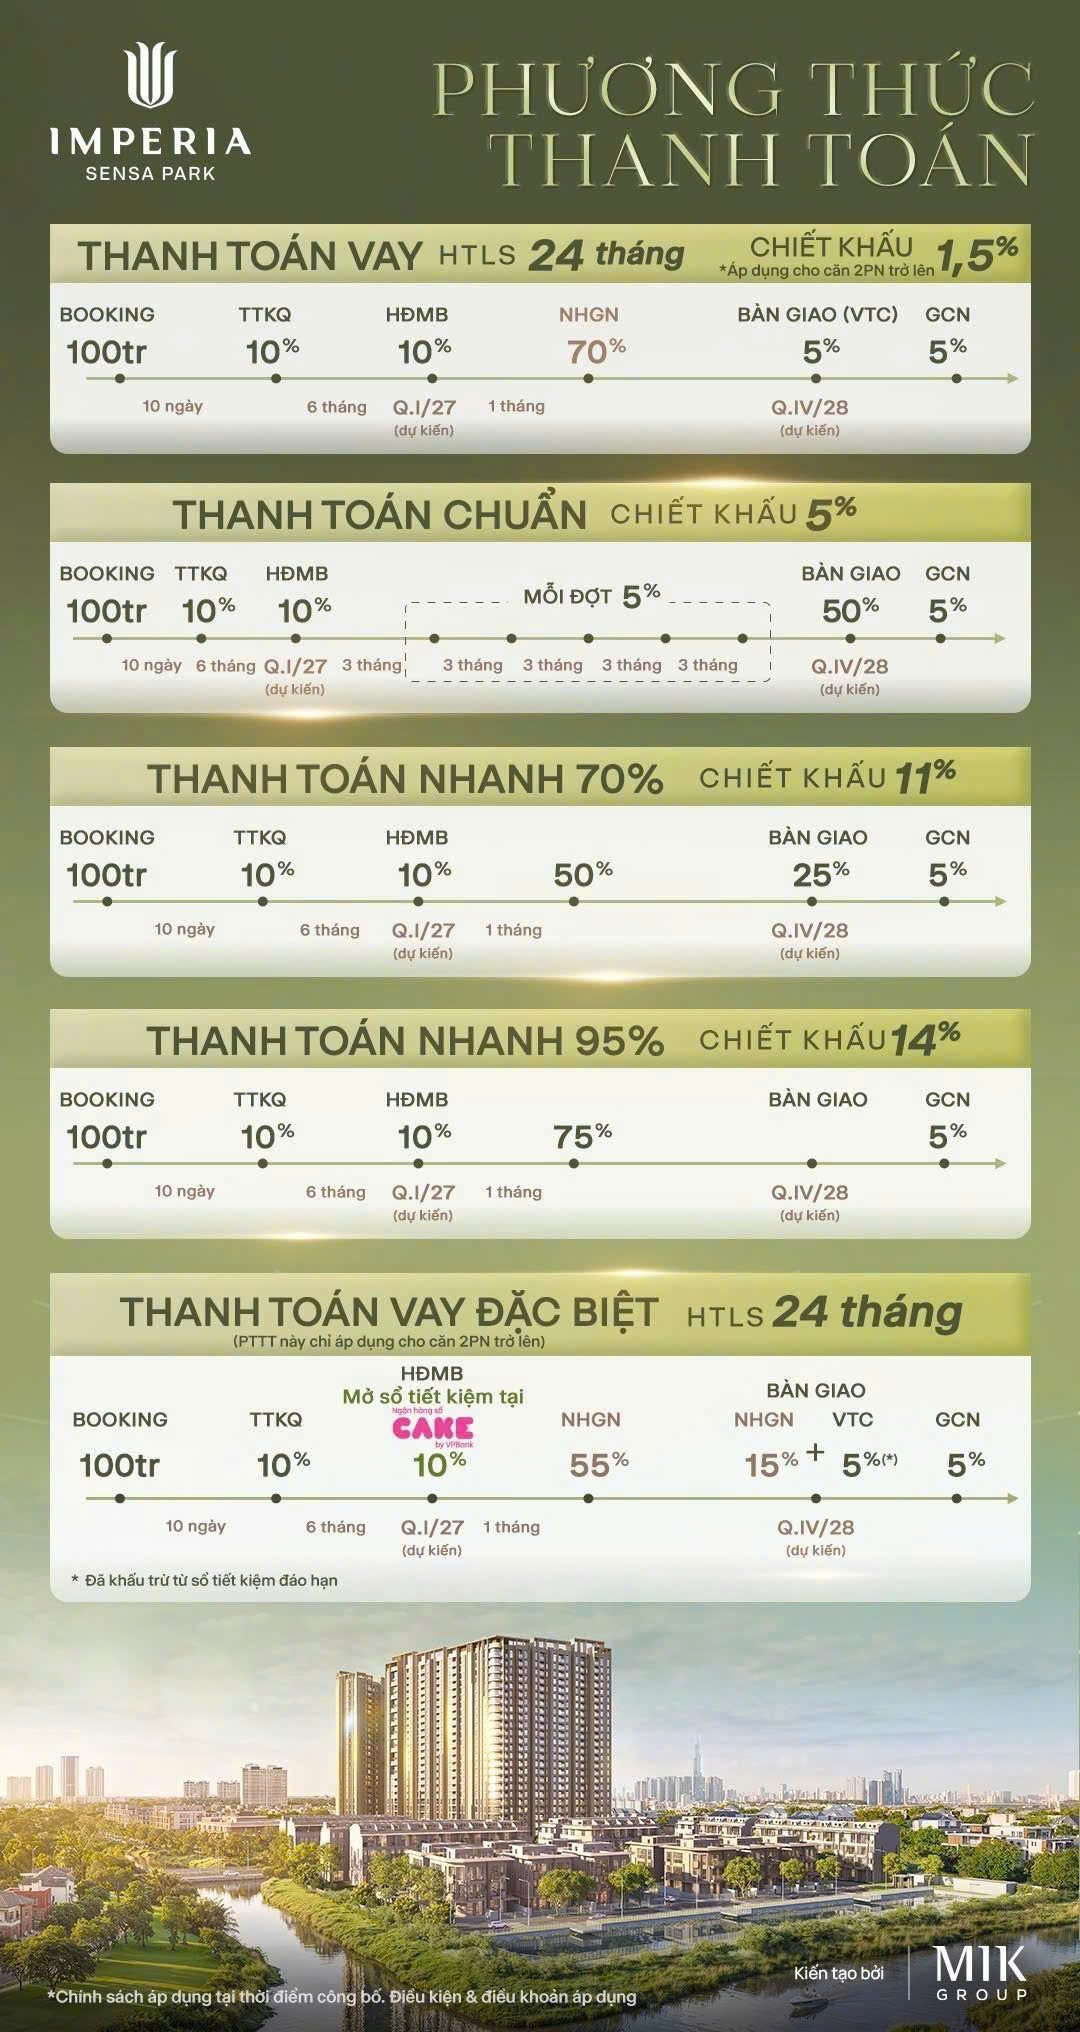
| Scheme | Discount | Paid before handover | Notes |
|---|---|---|---|
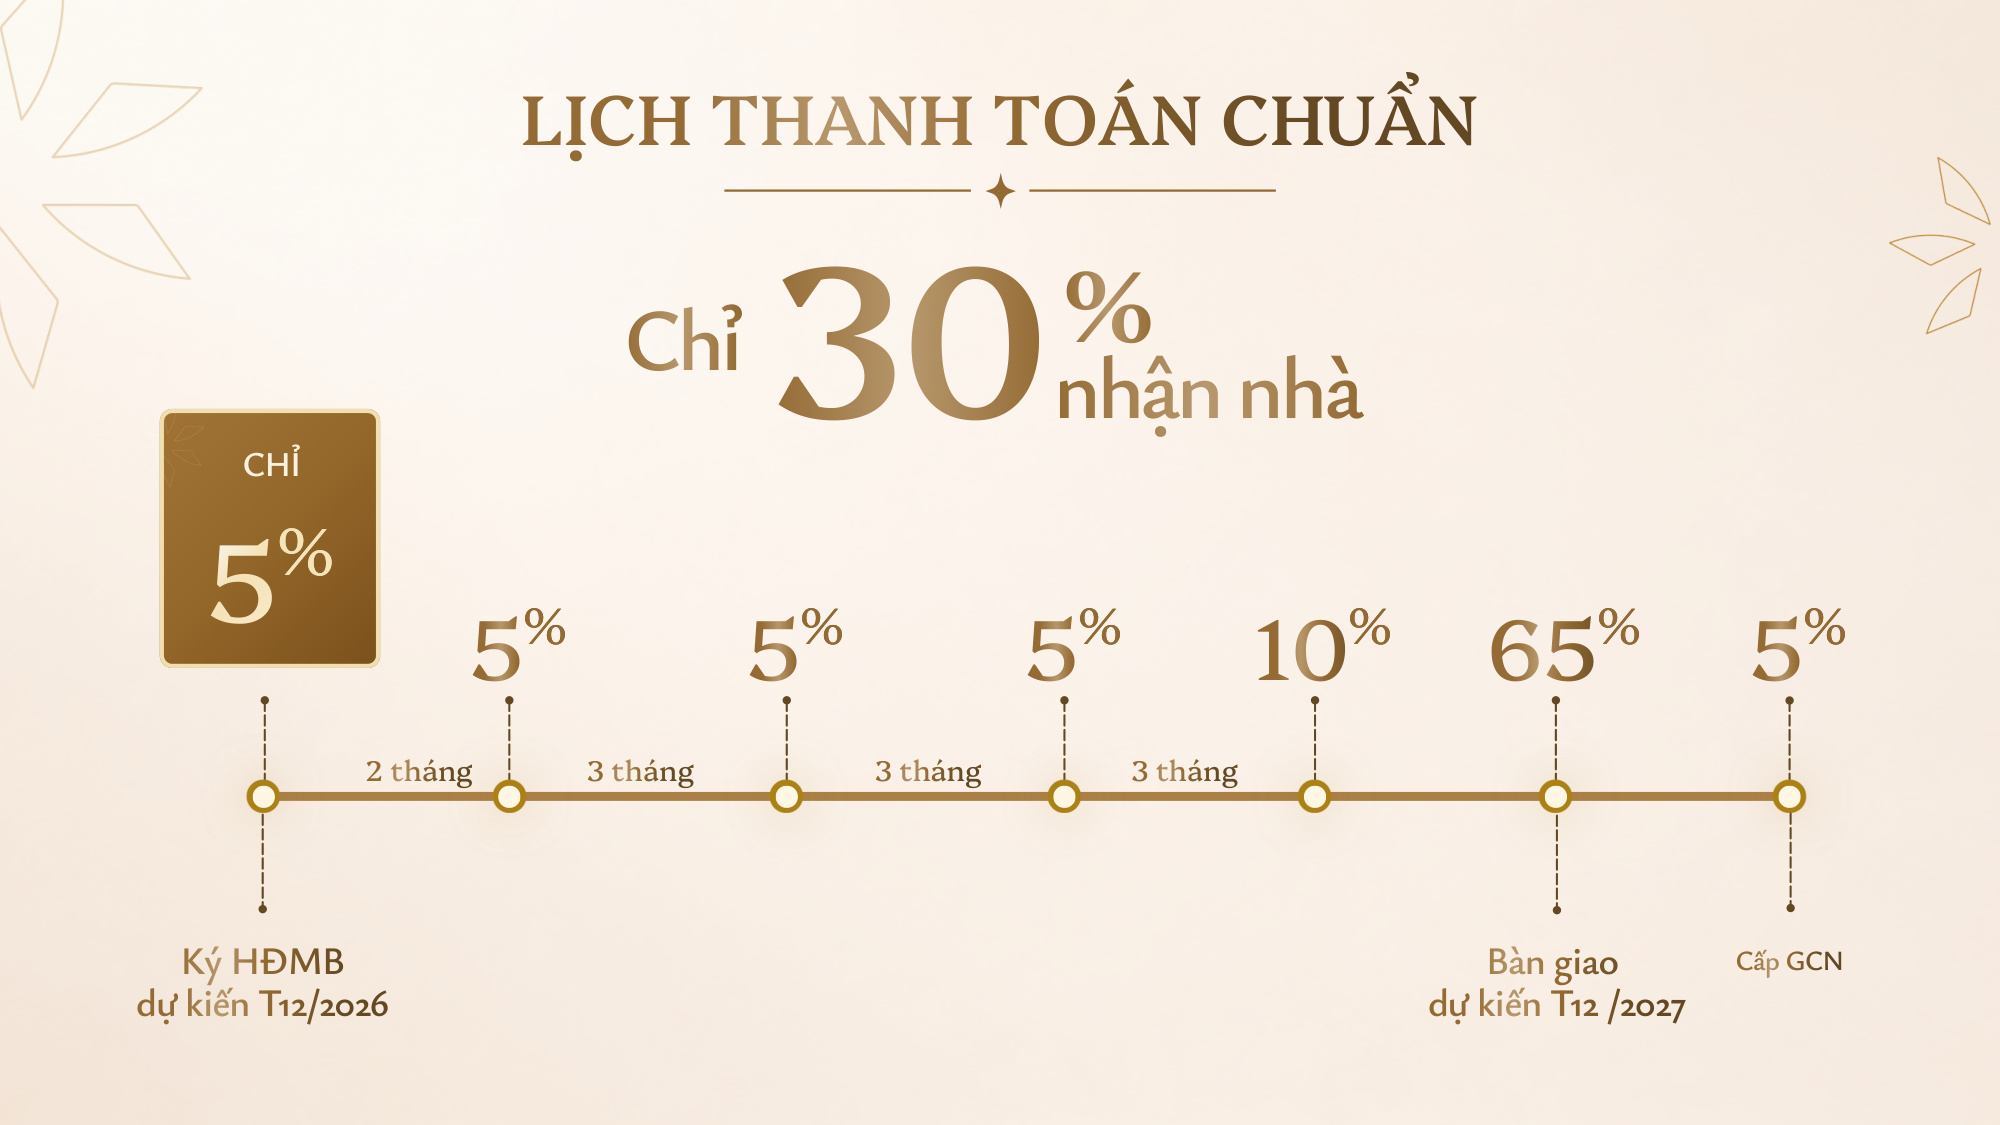
| Standard payment | 5% | 45% (10% at the escrow agreement, including the VND 100 million booking, 10% at SPA, five 5% instalments) | Handover 50%, certificate 5% |
| Fast payment 70% | 11% | 70% (10% + 10% + 50% one month after SPA) | Handover 25%, certificate 5% |
| Fast payment 95% | 14% | 95% (10% + 10% + 75% one month after SPA) | Certificate 5% |
| Loan payment | 1.5% (2-bedroom units and above) | 20% (bank disburses 70%) | 24-month interest support, handover 5%, certificate 5% |
| Special loan payment (2-bedroom and above) | No scheme discount | 20%, including a 10% CAKE savings account | Bank disburses 55%, handover 15% bank and 5% buyer, 24-month interest support |
Expected timeline: the escrow agreement 10 days after the booking, the SPA about 6 months later (Q1 2027) and handover in Q4 2028. The fast and loan schemes put their big instalment one month after the SPA.
Starting prices by unit type
According to the developer’s reference sheets of September and October 2026 (excluding VAT and maintenance fee):
| Unit type | Gross floor area (m²) | Starting price |
|---|---|---|
| Studio | 35.2 | VND 3.4 billion |
| 1BR+ | 52.2 to 52.6 | VND 5.0 billion |
| 2BR | 70.0 to 94.4 | VND 6.0 billion |
| 3BR | 90.0 to 104.2 | VND 8.3 billion |
These are “from” prices, not prices of individual units. The special loan scheme applies only to 2-bedroom units and above; 1BR+ and Studio units do not take part.
Worked example: a 3-bedroom unit at VND 8.3 billion
I used the developer’s own sheet for a 3BR unit at VND 8.3 billion excluding VAT, in the Early Bird window of 19 to 25 October 2026 (2% for units of 2 bedrooms and above) with VAT estimated at 10%:
| Scheme | Total discount (including Early Bird) | Price after offers (excl. VAT) | Price incl. 10% VAT |
|---|---|---|---|
| Standard (5%) | VND 581 million | VND 7.719 billion | VND 8.491 billion |
| Fast 70% (11%) | VND 1.079 billion | VND 7.221 billion | VND 7.943 billion |
| Fast 95% (14%) | VND 1.328 billion | VND 6.972 billion | VND 7.669 billion |
| Loan (1.5%) | VND 290.5 million | VND 8.010 billion | VND 8.810 billion |
| Special loan | VND 166 million | VND 8.134 billion | VND 8.947 billion |
The gap between fast 95% and the special loan scheme is about VND 1.28 billion (including VAT), roughly 15% of the unit’s price excluding VAT. After Early Bird ended, each scheme lost about 2% of discount compared with the table above.
Fast-payment discounts: what interest rate are they really?
I converted the discounts into an implied interest rate by comparing cash flows with the standard scheme, assuming booking in November 2026, SPA in March 2027 and handover in October 2028:
- Fast 70% (11% discount): equivalent to about 12.8% per year on the money paid early.
- Fast 95% (14% discount): equivalent to about 11.8% per year.
Both are higher than ordinary savings rates, so for buyers with cash, fast payment makes more sense than standard payment. But fast 95% is not “better” than fast 70% in terms of return: it adds only 3% of discount while requiring 25% more to be paid much earlier. Many buyers still choose 95% because they want the lowest final price and no loan. If you have other investments that earn over 12% per year, fast 70% is the better balance.
The “Settle in, Earn more” program and the CAKE savings account
This is the part most worth reading closely. The program applies to buyers of apartments (including Duplex units). Buyers who choose the special loan scheme must join; buyers on other schemes may join voluntarily, at the latest when signing the SPA.
How it works
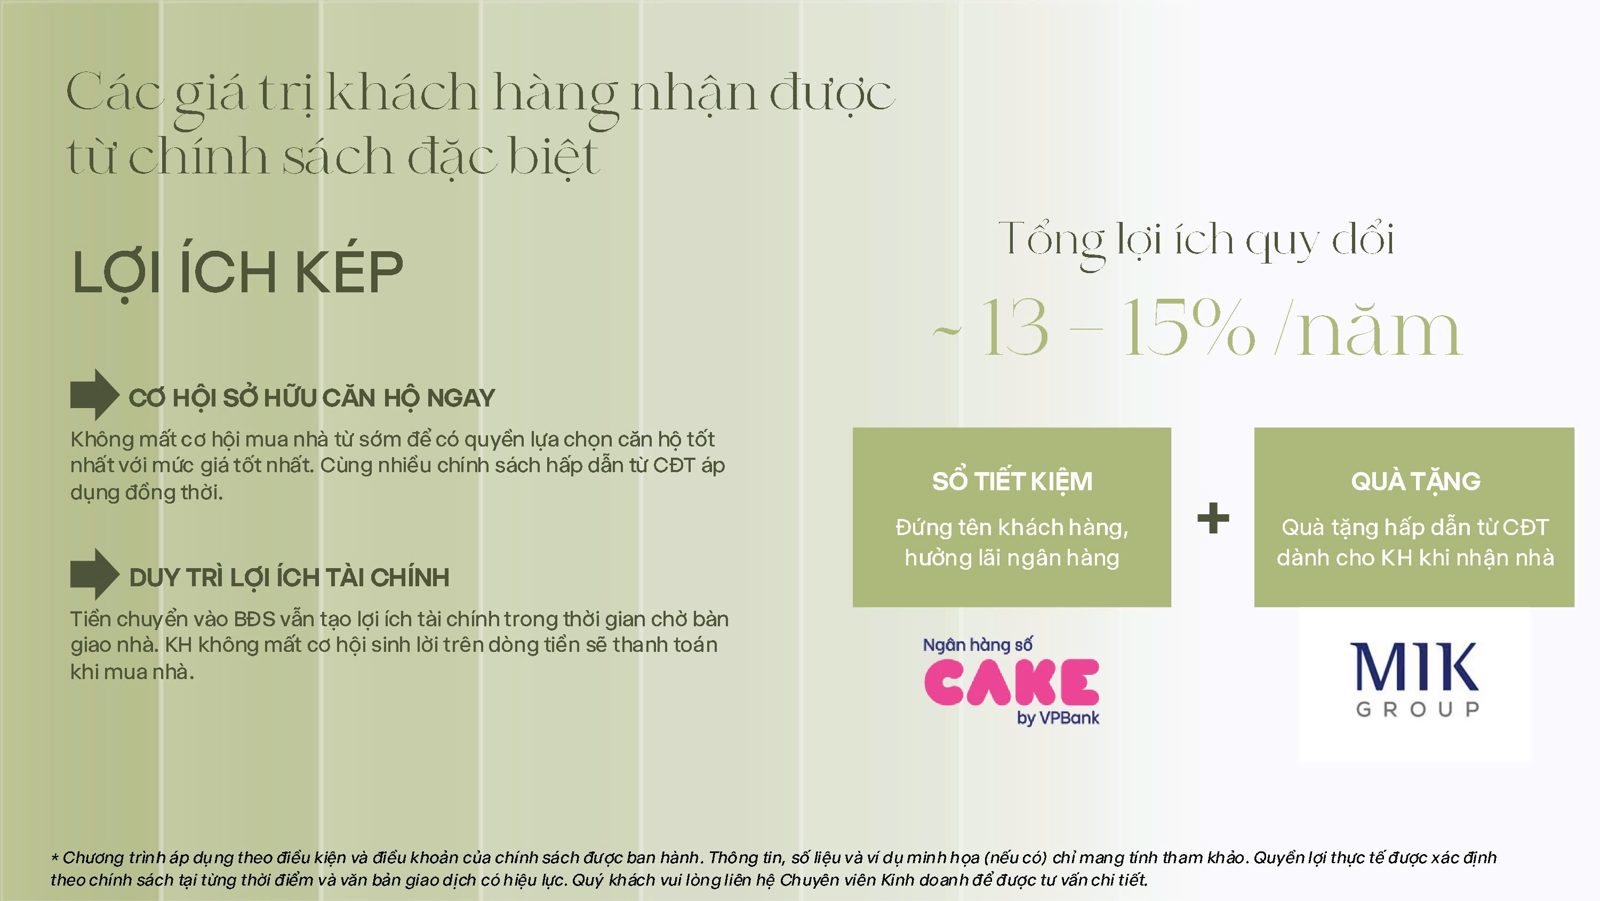
- The buyer opens a savings account at the digital bank CAKE by VPBank, with a minimum amount equal to 10% of the apartment’s price (excluding VAT and maintenance fee) and a term of 18 to 24 months.
- The account is blocked under a three-party agreement between the buyer, the bank and the developer, but still belongs to the buyer and is covered by deposit insurance under the law.
- When the developer issues the notice of handover, the bank releases the account and transfers exactly 10% of the price to the developer to pay the handover instalment. The interest and any surplus belong to the buyer.
- The buyer also receives a developer gift on handover: Studio VND 30 million, 1BR+ VND 45 million, standard 2BR VND 60 million, large 2BR VND 70 million, 3BR VND 80 million.
The returns the developer publishes
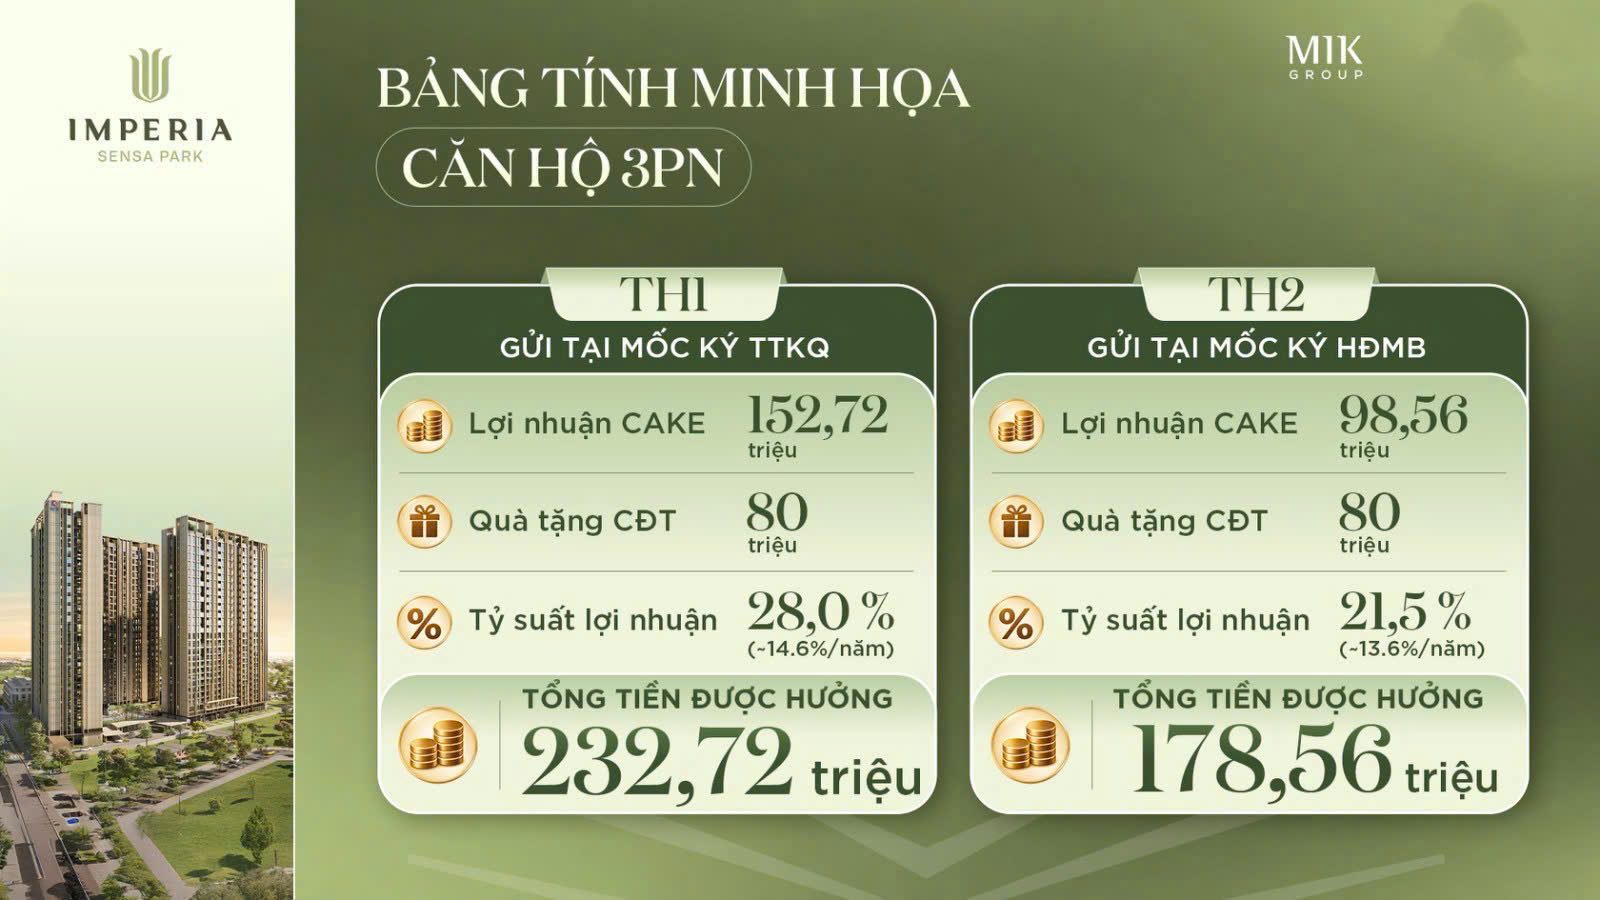
The developer’s illustration for a 3BR unit at VND 8.3 billion (deposit of VND 830 million):
| Case | CAKE interest | Gift | Total received | Return |
|---|---|---|---|---|
| Case 1: deposit at the escrow signing (Nov 2026), 9.6%/year, about 23 months | VND 152.72 million | VND 80 million | VND 232.72 million | 28.0% (about 14.6%/year) |
| Case 2: deposit at SPA signing (Mar 2027), minimum 7.5%/year, about 19 months | VND 98.56 million | VND 80 million | VND 178.56 million | 21.5% (about 13.6%/year) |
I checked the interest math: VND 830 million x 9.6% x 23/12 equals VND 152.72 million, and VND 830 million x 7.5% x 19/12 equals VND 98.56 million. The arithmetic is correct. What matters is how to read the numbers.
Four things to understand so you are not misled
- The 13 to 15% yearly return is calculated on 10% of the apartment’s value, not on the whole unit. That is the buyer’s own money, locked for almost two years, so “a 13 to 15% yearly benefit” is true only for that 10%.
- The 9.6% rate is only a reference. The applied rate is CAKE’s preferential rate schedule on the account opening date, only for project buyers on the list confirmed by the developer, with a term of 18 to 24 months. Once opened, the rate stays fixed for the chosen term.
- Opening early pays more than opening late. Case 1 beats case 2 by about VND 54 million of interest on a VND 8.3 billion unit, because of the higher rate and longer deposit. A buyer can open the account and the savings book as early as the escrow signing.
- Binding conditions: no withdrawing, closing, pledging or transferring the account during the blocked period without the developer’s written consent. Early withdrawal earns only the non-term rate and forfeits the gift. If handover is later than the term, the account auto-renews at the listed rate of that time.
Who cannot join?
The program does not yet apply to foreign buyers, because opening a CAKE account requires a Vietnamese citizen with a valid chip-based ID card. Vietnamese organizations can join, but account opening takes longer. If the contract is assigned, the new buyer must open a new account at the prevailing rate.
Is the special loan scheme really a “loan”?
Under the special loan scheme, the schedule is 10% at the escrow signing, 10% as a CAKE savings account at the SPA, 55% disbursed by the lending bank, and at handover 15% bank disbursement plus 5% paid by the buyer, then 5% for the certificate. So the buyer needs about 25% of own capital (10% + 10% + 5%) plus the 5% certificate payment, and bears interest after the support period. Interest support lasts 24 months; per the early October policy it was expected to end on 30 April 2029, about 6 months after the expected handover date. The developer’s sheet shows no payment-scheme discount for this option, so its final price is the highest of the five. The benefit lies in the supported interest and the savings interest.
Choosing a scheme by your needs
- Cash in hand, lowest final price: fast 95% (14%) or fast 70% (11%), depending on how much capital you want to lock.
- Buying to live in, moderate capital: special loan combined with the savings account, if you are a Vietnamese citizen and your loan file qualifies.
- Flexible without borrowing: standard payment, optionally adding the voluntary savings account to earn interest and the gift.
- Foreign buyers: the savings program does not apply yet, so consider standard or fast.
Points to confirm with the developer
- The latest policy after Early Bird (ended 25 October 2026): the current discount for each scheme.
- The list of buyers entitled to CAKE’s preferential rate and the rate on the account opening date.
- The handover date: the price sheet says Q4 2028, the CAKE Q&A says October 2028.
- The conditions of the 24-month interest support and when it ends (30 April 2029 per the early October policy).
- The rules for assigning the contract once a blocked savings account exists.
Detailed floor plans Imperia Sensa
View detailed floor plans by tower, floor and unit →
For the project overview, location and amenities, see Imperia Sensa Park, green living right at the Metro station.
Frequently asked questions about Imperia Sensa Park sales policy
How many payment schemes does Imperia Sensa Park have?
Five: standard, fast 70%, fast 95%, loan, and special loan (2-bedroom units and above).
What is the highest discount?
Fast 95% gives 14%, fast 70% gives 11%, standard 5% and loan 1.5% for units of 2 bedrooms and above, before phase offers such as Early Bird.
What are the starting prices?
Studio about VND 3.4 billion, 1BR+ about VND 5 billion, 2BR about VND 6 billion and 3BR about VND 8.3 billion, excluding VAT and maintenance fee, per the developer’s reference sheet.
What is the “Settle in, Earn more” program?
The buyer places a CAKE savings deposit equal to 10% of the apartment price for 18 to 24 months, blocked until handover, earns a preferential rate for project buyers and receives a developer gift on handover.
Can foreign buyers join the program?
Not at present, because opening a CAKE account requires a chip-based ID card of a Vietnamese citizen.
When is the SPA and when is handover?
The SPA is expected in Q1 2027 and handover in Q4 2028.
OFFICIALLY DISTRIBUTED BY 168 PROPERTY
168Property is proud to be the official distributor of Imperia Sensa Park, accompanying investors through every stage of advisory, transaction and after-sales asset management. With an experienced team who understand the market and offer multilingual support, 168Property is committed to giving international investors a transparent, professional transaction experience that maximizes returns.
Contact 168Property today so you do not miss the opportunity to invest in the Ho Chi Minh City real estate market!
- Website: www.168property.vn
- Hotline: 0932.698.168
- Email: info@168property.vn
More information: developer MIK Group and digital bank CAKE by VPBank.
Disclaimer: Information, images and calculations in this article are compiled from the developer’s documents and 168Property’s own calculations as of November 2026, for reference only and subject to change. Return conversions are estimates based on expected dates, not a promise of profit. Renderings are for illustration only. Official terms are those of the sale and purchase agreement.
- Orchard Collection Sycamore Binh Duong: CapitaLand’s Final Apartment Zone
- The Orchard Sycamore Binh Duong: CapitaLand Townhouses and Villas, Already Handed Over
- Masteri An Phu Project Introduction
- Vinhomes Green Paradise Can Gio Progress November 2026: Overview, Temple, Stadium And Townhouse Rows
- THE BERKLEY – LUXURY APARTMENTS IN THAO DIEN
Leave a Reply